McDonald's Price Target Cuts
Major Wall Street Analysts Lower McDonald's Price Targets Amid Spending Concerns
Anonymous
Key Points
1
Deutsche Bank analyst Lauren Silberman said the key issue ahead of McDonald’s investor day was the company’s expected contribution to the upcoming 10-year U.S. restaurant remodel cycle, particularly the implications for spending.
2
Deutsche Bank anticipated that McDonald’s unit-growth outlook could moderate because of global headwinds and potentially tighter capital availability as the U.S. system approaches its reinvestment cycle.
3
McDonald’s derives about 62% of its income from franchise royalties and rents, with the balance coming from company-operated restaurants, highlighting the importance of its franchising model to the business.
4
GuruFocus gave McDonald’s a GF Score of 69 out of 100; the company’s profitability and valuation were identified as strengths, while its lower momentum ranking was a relative weakness.
5
McDonald’s operates more than 45,000 restaurants in over 100 markets and generates nearly $139 billion in systemwide sales, providing scale and international reach beyond the analyst target-price changes.
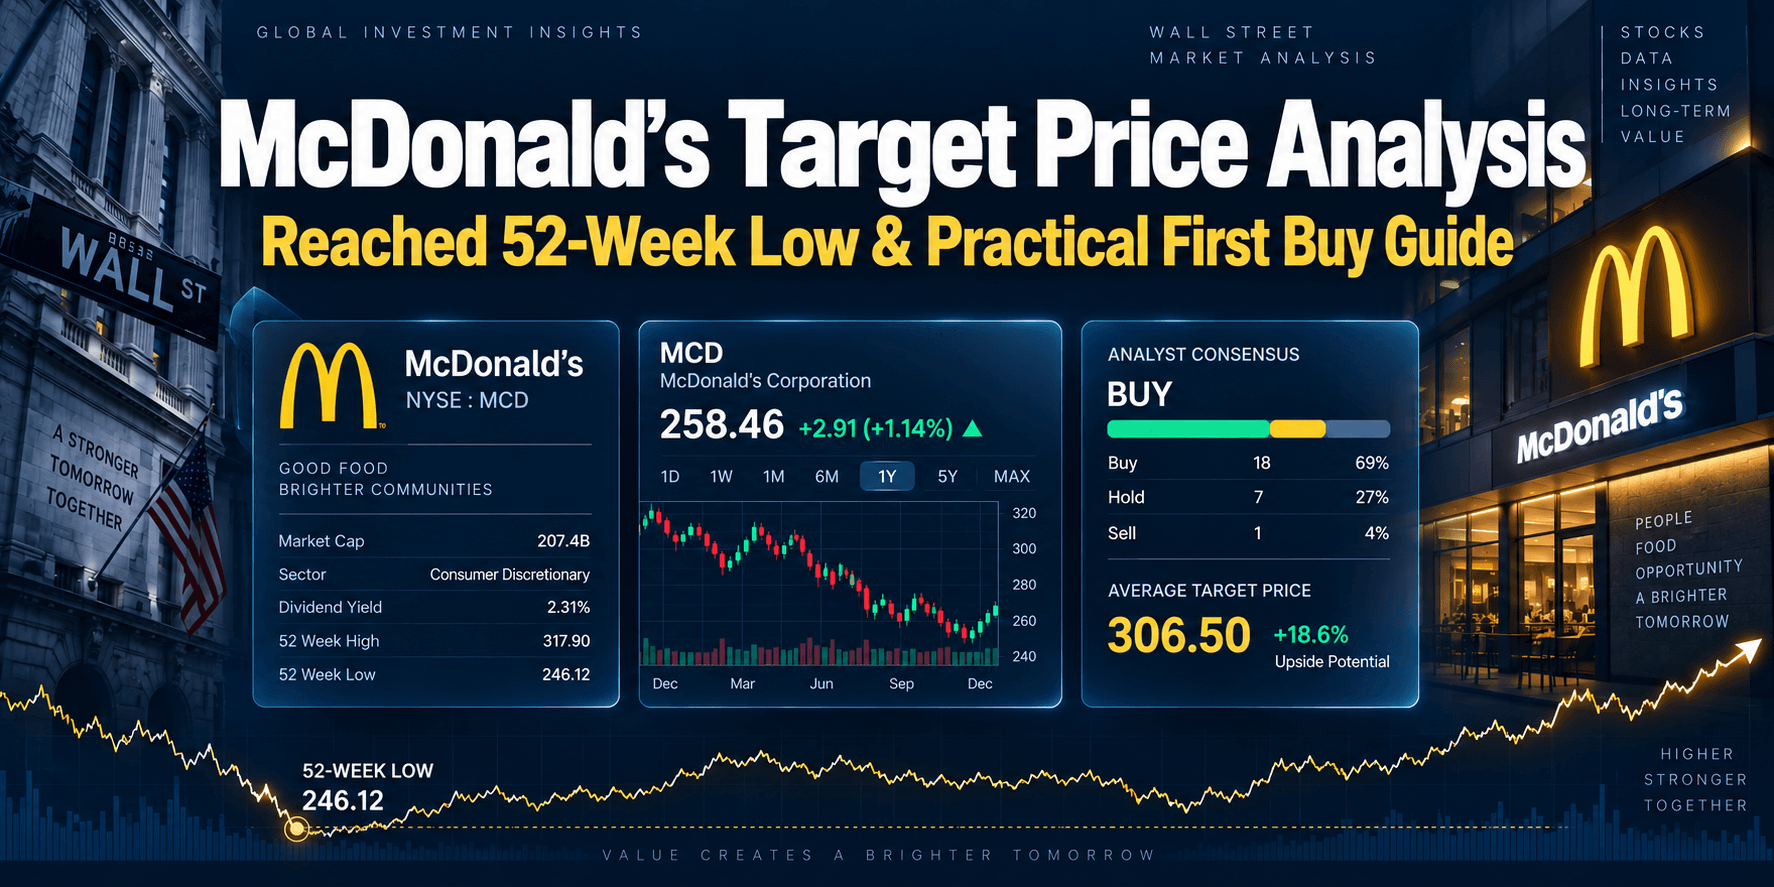
McDonald's faces a more cautious Wall Street outlook as major analysts cut their price targets while keeping their ratings largely unchanged. Deutsche Bank lowered its target from $325 to $300 while keeping a Buy rating, RBC Capital cut $295 to $290 on a Sector Perform rating, and Morgan Stanley reduced $319 to $308 while maintaining Equal-Weight. Citigroup also cut its target from $345 to $310, though it kept a Buy rating. The moves reflect concerns about consumer spending pressure, competitive challenges, and a looming U.S. restaurant remodel cycle.
Despite the target cuts, GuruFocus data shows McDonald's stock may trade below its intrinsic value, with a price-to-earnings ratio sitting below its five-year median. The company operates over 45,000 restaurants across 100+ markets and generates nearly $139 billion in systemwide sales. Its business model remains strong, with 62% of income from franchise royalties and rents, giving it a stable foundation despite the analyst caution.
Remodel Cycle Creates Spending Uncertainty
McDonald's faces a critical test ahead with its investor day as the company prepares for a major 10-year U.S. restaurant remodel cycle. Deutsche Bank analyst Lauren Silberman flagged this reinvestment push as a key concern, questioning what the spending demands will mean for profitability and capital allocation. The analyst worry centers on how much the company will need to invest to modernize its aging U.S. restaurant base.
The remodel cycle threatens to crimp McDonald's growth trajectory. Deutsche Bank expects the company's unit-growth outlook could slow due to global economic headwinds and tighter capital availability as the U.S. system gears up for heavy reinvestment. This creates a timing problem: while McDonald's builds new restaurants globally, it must simultaneously pour resources into fixing older locations at home.
Consumer Spending Headwinds Weigh on Outlook
Analysts cited mounting pressure on consumer spending as a reason for caution. Market uncertainty and potential tightening in household budgets could hurt McDonald's, which relies heavily on customers with limited discretionary income. RBC Capital and other firms worry that economic slowdown could pinch traffic at restaurants, especially in developed markets where competition for fast-food dollars remains intense.
Competitive conditions also pressure margins. Quick-service restaurant rivals are fighting aggressively for market share through promotions and value offerings. This battle makes it harder for McDonald's to raise prices or protect margins, even as labor and commodity costs remain elevated. The analyst cuts reflect a belief that headwinds will persist before improving.
Valuation Still Attractive Despite Downgrades
The price target cuts don't necessarily mean McDonald's stock is overvalued. GuruFocus assigned the company a GF Score of 69 out of 100, highlighting strong profitability and cheap valuation as key strengths. The stock's price-to-earnings ratio remains below its five-year average, suggesting it may offer value even after the analyst downgrades.
One weakness GuruFocus identified is lower momentum — the stock has underperformed recently and may continue to lag in the near term. However, the company's massive scale, international presence, and stable franchise-based business model provide long-term support. Citigroup and Deutsche Bank both kept Buy ratings despite cutting targets, signaling belief in the long-term story even if near-term challenges persist.
Sentiment
Mostly NegativeNEGATIVENEUTRALPOSITIVE
Publishers
15
Articles
23
Reach
38
A
AnonymousAuthor


