Rising Borrowing Costs
Mortgage Rates Rise Across the U.S., UK and Switzerland Amid Inflation Pressures
Anonymous
Key Points
1
The Mortgage Bankers Association said five-year adjustable-rate mortgages were about 1 percentage point cheaper than 30-year fixed loans, with the 5/1 ARM offering a fixed rate for its first five years before adjusting with market conditions.
2
Despite the broader rise in US mortgage costs, the five-year adjustable-rate mortgage fell 13 basis points to 6.10% during the week ending September 18.
3
In the UK, Moneyfacts estimated that a typical borrower taking out a two-year fixed mortgage was paying roughly £150 more per month than if they had secured the loan at the start of the year.
4
Moneyfacts finance expert Rachel Springall said remortgaging activity is expected to surge as borrowers leave cheaper fixed-rate deals, and suggested lenders consider extending product-transfer windows to give existing customers more time to lock in new rates.
5
The US housing affordability squeeze has become a political liability: a Reuters/Ipsos poll cited in the report found that only 17% of respondents approved of President Donald Trump’s handling of the cost of living, which respondents identified as the leading issue influencing their November vote.
Mortgage rates have jumped sharply across the United States, United Kingdom, and Switzerland, putting new pressure on homebuyers and borrowers. In the US, the average 30-year fixed rate hit 7.12% for the week ending September 18—the highest level since May 2024 and above 7% for the first time since early 2025, according to Mortgage Bankers Association. Rising Treasury yields, persistent inflation driven by energy costs, and the Federal Reserve's recent quarter-point rate increase to 3.75%-4.00% have all pushed borrowing costs higher.
The squeeze is hitting homebuyers hard. In the UK, two-year fixed rates climbed to 5.88%, meaning typical borrowers now pay roughly £150 more per month than they did at the start of the year, according to Moneyfacts. Even in Switzerland, where inflation remains moderate, five-year rates reached 1.83% and 10-year loans exceeded 2%. The rises are reshaping how people borrow—nearly one in ten US mortgage applicants are now choosing riskier adjustable-rate mortgages that start lower but can jump later.
Fed Rate Hike and Treasury Yields Fuel American Mortgage Surge
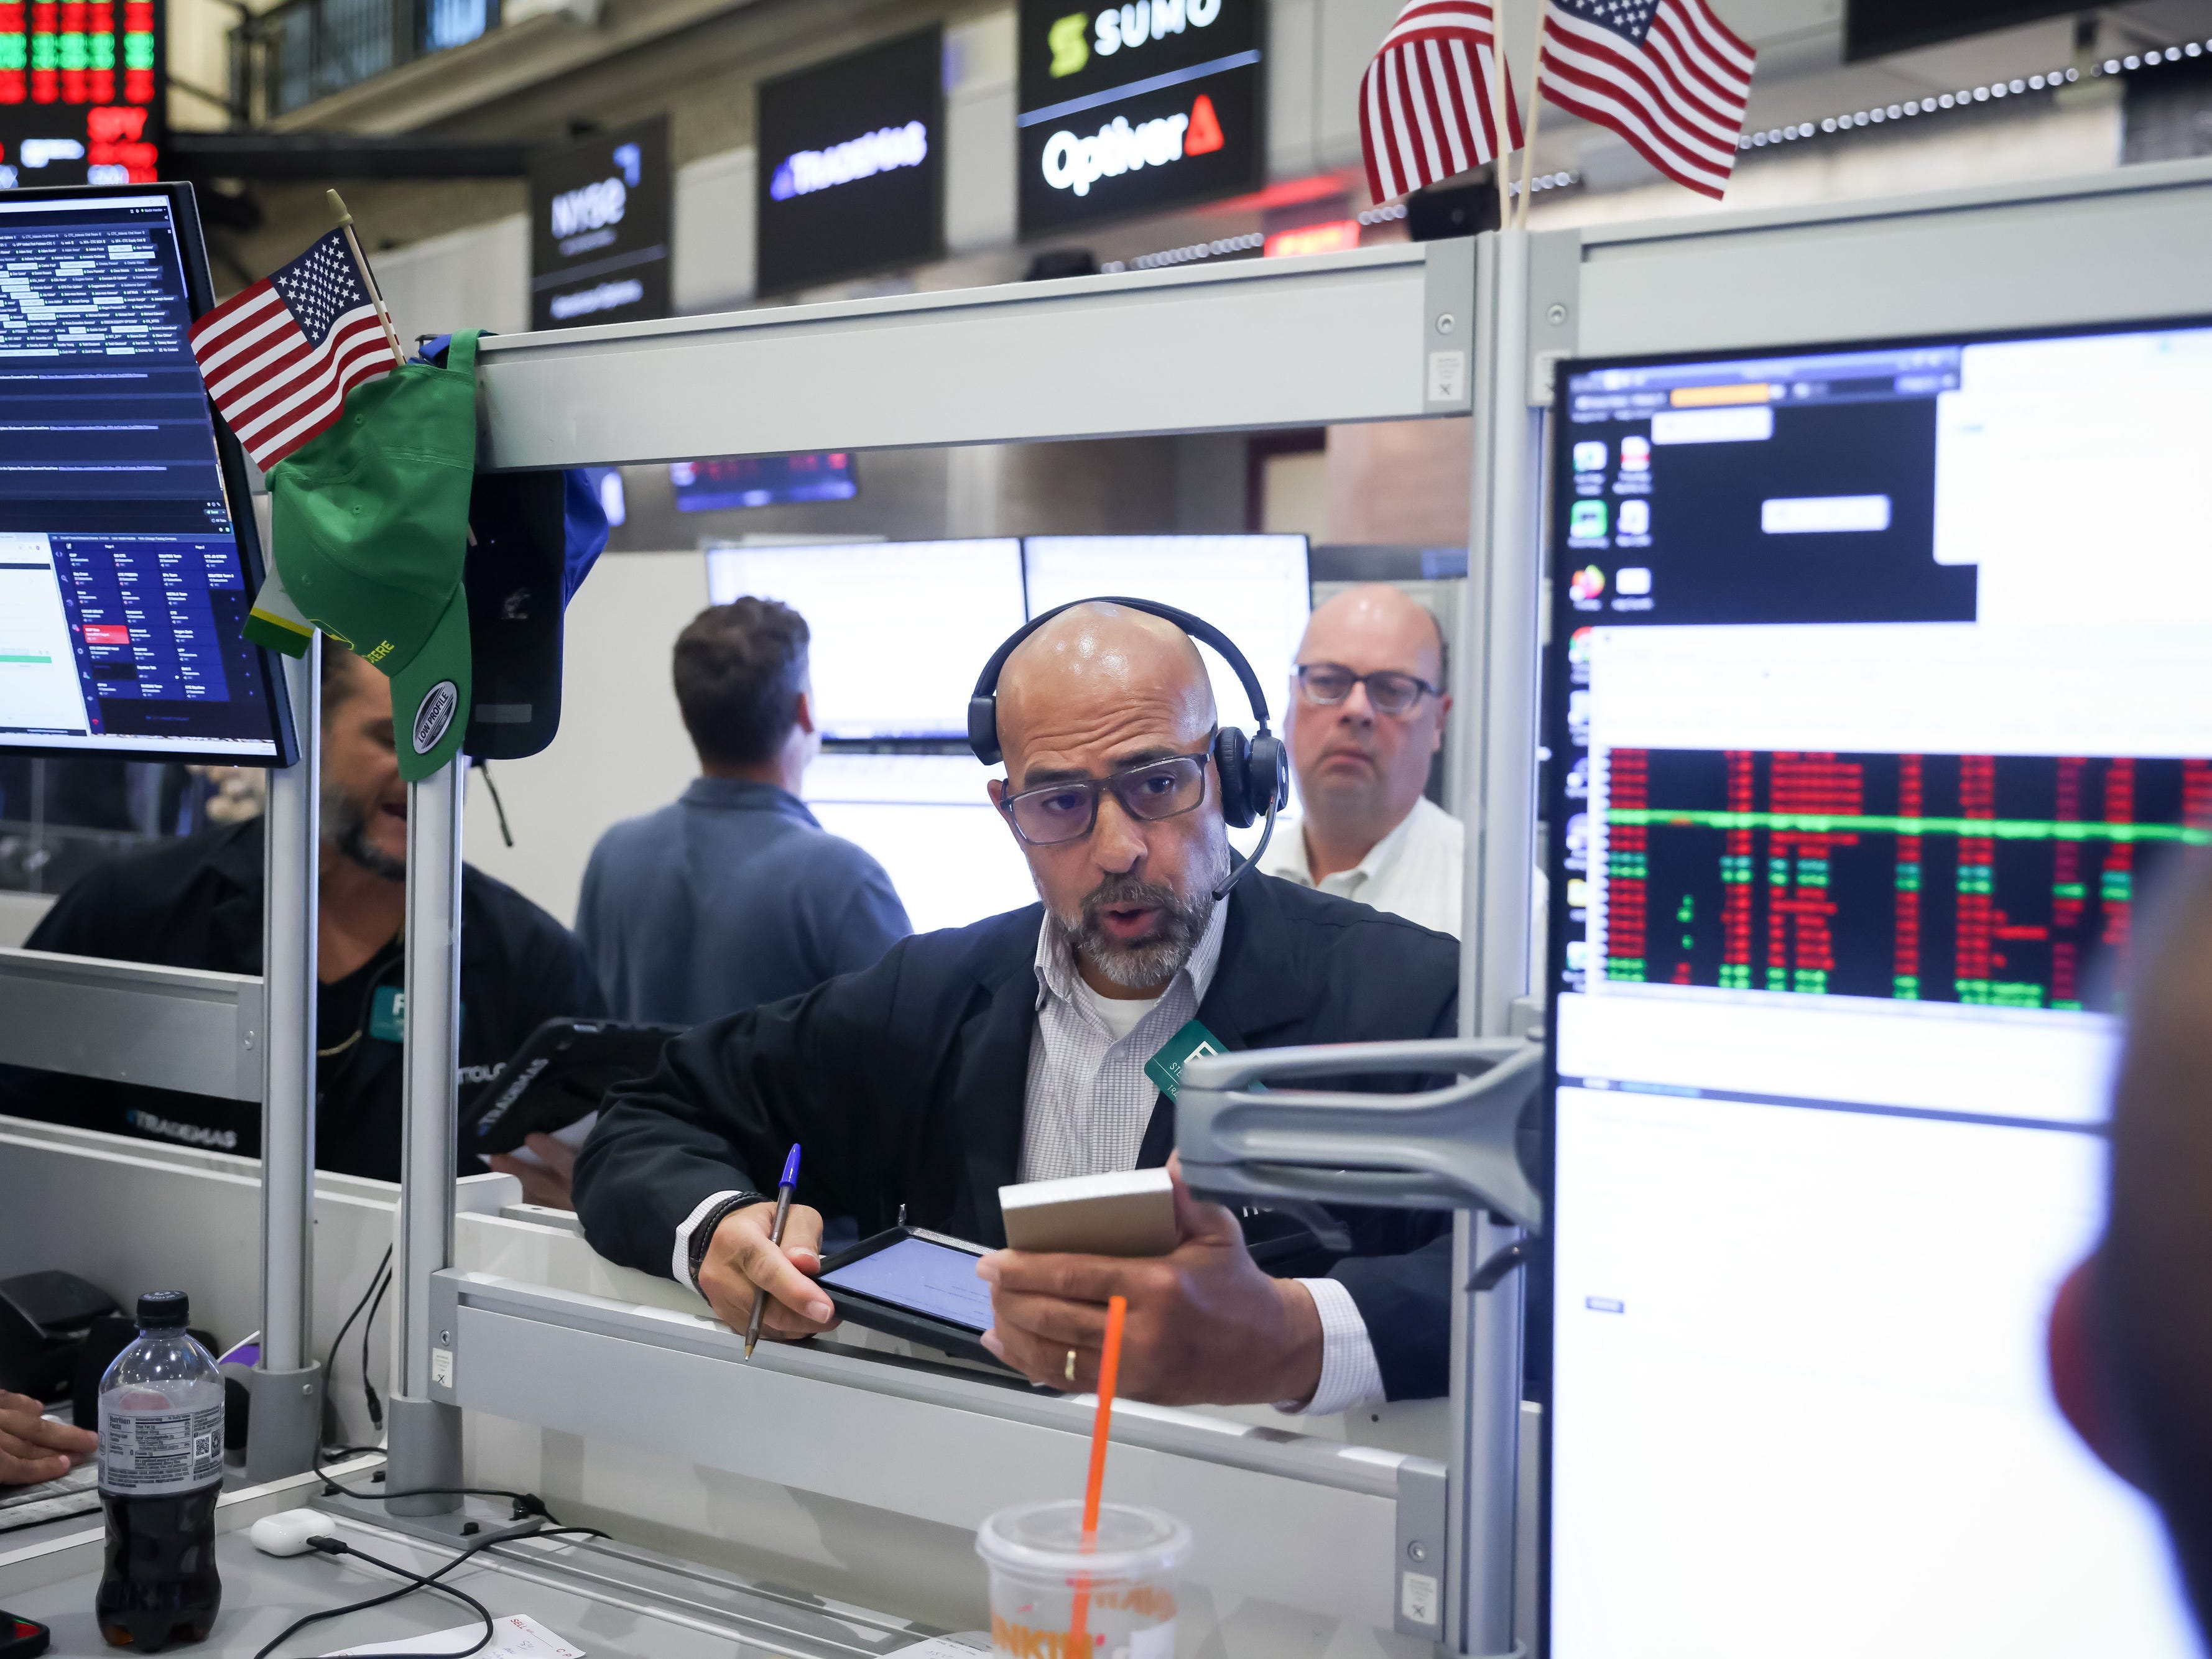
The Federal Reserve's move to raise its benchmark rate to 3.75%-4.00% in mid-September accelerated the climb in mortgage costs. When the central bank raises rates, long-term borrowing costs—like mortgages—typically follow because lenders expect future inflation. The 10-year Treasury yield jumped to around 5.01%, a new post-2008 financial crisis peak, signaling that investors demand higher returns to hold government debt. Business Insider reported that stocks tumbled as bond yields surged, rattling both investors and consumers.
The numbers tell the story. The MBA survey showed the 30-year fixed rate rose 15 basis points to 7.12% for the week ending September 18. Freddie Mac reported a slightly lower 6.95%, a difference caused by how the two agencies time their surveys and count fees. Purchase demand slipped 1% week-over-week, while refinance activity dropped 3%—standing 62% below levels from the same period last year. Fewer borrowers are refinancing because rates are much higher than the deals they locked in during 2023 and 2024.
Adjustable-Rate Mortgages Gain Appeal as Savers Seek Lower Payments
As fixed rates climbed, borrowers turned to adjustable-rate mortgages (ARMs) as a cheaper short-term option. The 5/1 ARM—which holds a fixed rate for five years before adjusting—dropped 13 basis points to 6.10% during the same week, creating roughly a 100 basis point gap between ARMs and 30-year fixed loans. Mortgage Bankers Association noted that nearly one in ten new applications were for ARMs, double the typical share. A typical $250,000 loan at 6.10% saves about $168 per month compared to the 7.12% fixed rate, a savings that appeals to borrowers betting rates will fall within five years.
But financial experts warn that ARMs carry hidden risks. Once the fixed-rate period ends, payments can jump sharply if rates stay high or climb further. Traditional advisors urge caution, while mortgage brokers highlight the immediate monthly savings. The choice reflects deep anxiety about housing affordability. A Reuters/Ipsos poll found only 17% of Americans approve of President Donald Trump's handling of the cost of living—and housing costs are the leading issue voters say will influence how they vote in November.
British Borrowers Face Rising Costs and Rich Buyers Leverage Mortgages
The UK mortgage market is heating up too. Five-year fixed rates reached 5.92% and two-year rates 5.88%, driven by higher government borrowing costs, inflation, and expectations that the Bank of England will raise rates further. Moneyfacts calculated that a typical borrower taking a two-year fixed deal now pays about £150 more per month compared to rates available at the start of 2026. That adds up to £1,800 per year—a significant hit for middle-income families already stretched by rising living costs.
Meanwhile, wealthy British buyers are using mortgages in unexpected ways. High-net-worth individuals in London are increasingly taking out large mortgages of £5 million or more to finance expensive properties—not because they cannot afford to buy outright, but to preserve cash for higher-yielding investments. Moneyfacts finance expert Rachel Springall warned that remortgaging activity will surge as borrowers roll off cheaper fixed-rate deals signed years ago. She urged lenders to extend product-transfer windows to give existing customers more time to lock in new rates before rates climb further.
Switzerland's Strong Franc Shields Borrowers From Steeper Rate Rises
Switzerland's mortgage market has been spared the severity of rate increases seen in America and Britain. Five-year fixed rates reached 1.83% and 10-year loans exceeded 2%—still increases, but modest compared to global peers. The Swiss franc's strength and relatively moderate domestic inflation have kept demand for Swiss government debt stable, limiting upward pressure on borrowing costs. Economists expect further increases to remain limited unless inflation accelerates sharply or the Swiss National Bank signals more aggressive rate hikes ahead.
Sentiment
Mostly PositiveNEGATIVENEUTRALPOSITIVE
Publishers
28
Articles
89
Reach
117
A
AnonymousAuthor


