Monsoon Weakness Hits Farming
Weak Monsoon Forces Indian Farmers to Cut Input Spending and Tractor Purchases
Anonymous
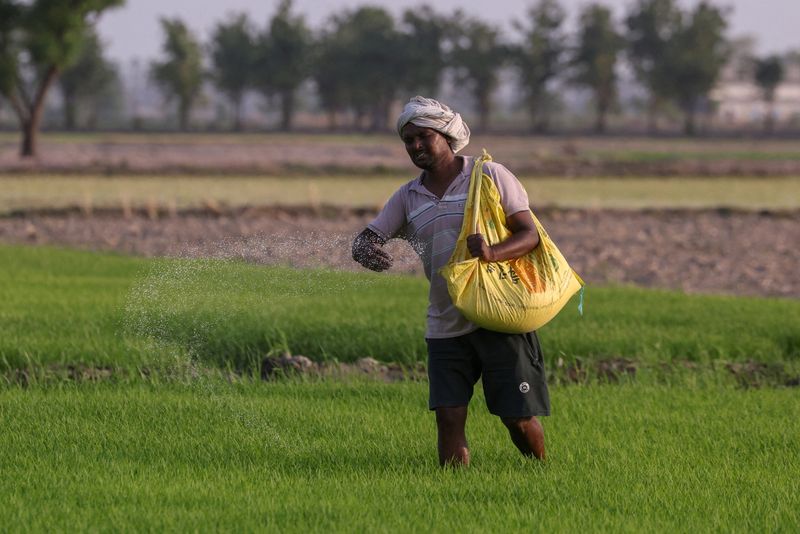
India’s southwest monsoon is running about 15% below normal and has been especially weak in September, raising concerns about crop yields, rural incomes and food inflation. Uncertainty over harvests is prompting farmers to conserve spending on pesticides, fertilizers and seeds, particularly herbicides and fungicides, while the farm-input industry faces intensifying competition and possible consolidation. The uneven distribution of rainfall is a major concern, with persistent deficits in eastern, northeastern and southern regions despite some improvement in central and northwestern India. Central India and the northwest—important production regions for crops including cotton, oilseeds, pulses, sugarcane and rice—have experienced smaller shortfalls that may cushion the broader impact on output and prices. The weaker farm outlook is also expected to slow tractor demand sharply, with wholesale volume growth projected at just 1% to 4% in FY27 after a 23.5% increase the previous year, although manufacturers’ margins may remain relatively stable.
Key Points
1
Nomura described the southwest monsoon as India’s weakest in a decade, with September rainfall about 25% below normal; the India Meteorological Department said monsoon withdrawal began from parts of West Rajasthan around September 19.
2
The regional crop impact is uneven: Central India has a 6% rainfall deficit and produces about 70% of India’s cotton, 57% of its oilseeds and 52% of its pulses, while the northwest has a 10% deficit and contributes more than half of the country’s sugarcane and over one-third of its rice.
3
The rainfall deficit is most severe in the South Peninsula, at 28% below normal, while the east and northeast are 26% below normal; the latter’s crop contribution is generally limited except for crops such as jute and mesta, although Assam’s tea production is particularly important.
4
Tractor demand data already show a divergence between wholesale and retail markets: August wholesale volumes rose 6.5% year on year, but retail registrations increased only 0.8%, suggesting that end-user demand is beginning to weaken after roughly 18 months of strong double-digit growth.
5
Despite the expected slowdown in tractor volumes, Icra expects manufacturers’ operating margins to remain stable, supported by operating leverage and relatively steady raw-material procurement costs.
Sentiment
Mostly NegativeNEGATIVENEUTRALPOSITIVE
Publishers
8
Articles
62
Reach
70
A
AnonymousAuthor