Rising Yields Strain Markets
U.S. 30-Year Treasury Yield Hits Highest Level Since 2002 Amid Bond Selloff
Anonymous
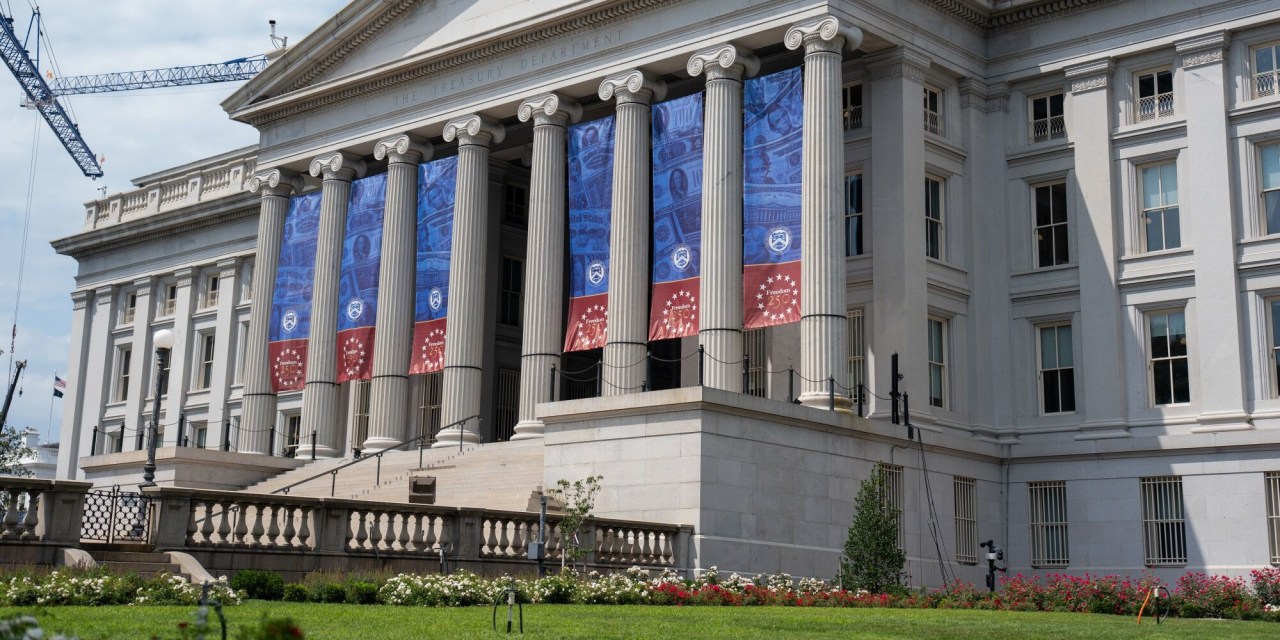
A broad government-bond selloff pushed the U.S. 30-year Treasury yield above 5.6%, its highest level since 2002, while the 10-year yield climbed to about 5.25%, a level last seen in 2007. Investors cited elevated oil prices, geopolitical tensions, inflation concerns, expectations that interest rates could stay higher or rise further, and heavy government borrowing. The rise continued despite softer U.S. consumer-confidence and job-opening data; New York Fed President John Williams said policymakers had time to assess incoming information, tempering expectations of an imminent rate hike. Higher yields supported the dollar and pressured stocks and gold, while analysts warned that rapidly rising borrowing costs could expose financial vulnerabilities, though some investors saw value in bonds. In Japan, yields remained near multi-decade highs, while India’s 10-year government bond yield reached a more-than-two-year high amid concerns about oil prices and global rates.
Key Points
1
A large corporate-bond sale added to pressure on long-term Treasuries: Paramount Skydance was seeking about $32 billion as part of a $52 billion financing package for its acquisition of Warner Bros. Discovery. A rates strategist said some of the move at the long end was likely related to the offering.
2
Market strategists pointed to a possible “light buyer’s strike” in Treasuries and the unwinding of the yen-funded carry trade—borrowing in yen to invest in higher-yielding assets—as additional contributors to the selloff.
3
John Roque of 22V Research examined 16 episodes over roughly five decades when the 10-year yield rose at a similarly rapid pace, saying each coincided with or preceded a financial disruption. “As sure as day follows night, when the 10-year Treasury yield rises, something gets knocked out,” he warned.
4
Some investors said yields were becoming attractive: R.J. Gallo of Federated Hermes said a 10-year yield around 5.27% was starting to look appealing based on growth potential, the inflation target and a risk premium, and could prompt institutional investors to shift money into fixed income.
Sentiment
Mostly NegativeNEGATIVENEUTRALPOSITIVE
Publishers
68
Articles
145
Reach
213
A
AnonymousAuthor


